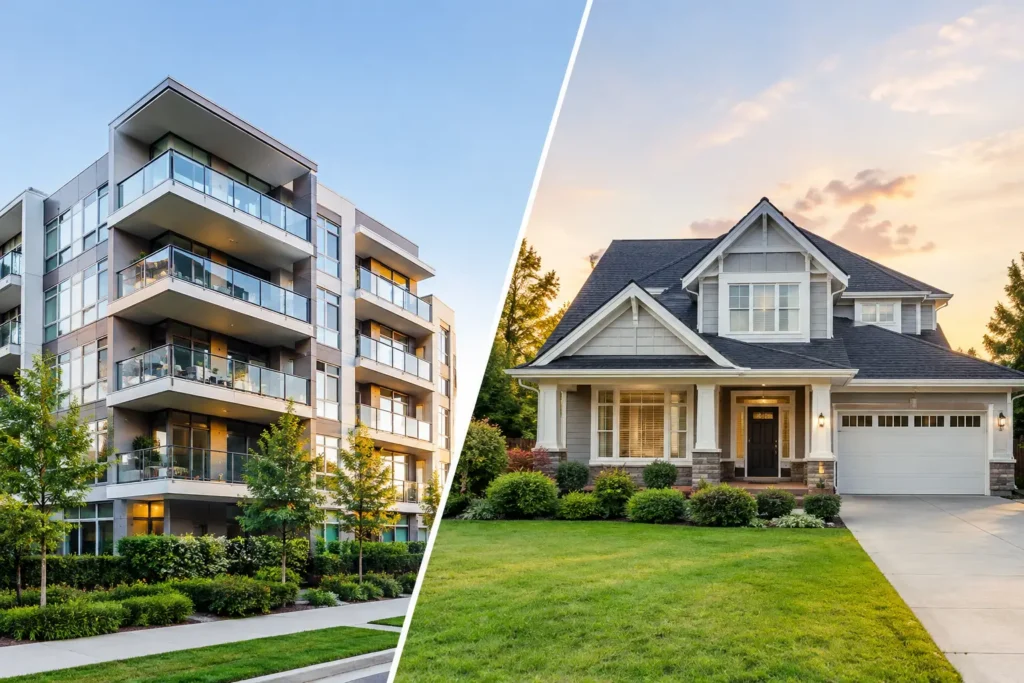
A surprise roof repair can change a homeowner’s budget overnight. A special assessment can do the same for a condo owner. That is why the condo versus house decision is not simply about square footage, curb appeal, or the purchase price. It is a decision about responsibility, monthly cash flow, lifestyle, and how much control you want over the property.
For buyers and investors in Ontario, the better fit depends on the property’s numbers as much as its address. A condo may offer a lower entry point and fewer exterior maintenance tasks. A house may offer more space, land, and flexibility. Each can be a strong home or rental asset when the ownership costs and obligations are understood before an offer is made.
Condo Versus House: Start With Ownership Responsibilities
A condominium unit gives you ownership of the space defined by the condominium declaration, while common areas and building systems are shared. Depending on the property, those common elements can include hallways, elevators, the roof, parking garage, landscaping, heating systems, amenities, and exterior walls. The condominium corporation oversees these shared components, funded largely through monthly condo fees.
With a detached, semi-detached, or freehold townhouse, you generally control the building and land. That means you decide when to replace the roof, repair a fence, update landscaping, or improve the exterior. It also means there is no condominium corporation coordinating those projects or spreading costs across other owners.
Neither arrangement is automatically easier. Condo ownership shifts many tasks to a managed structure, but it also means following corporation rules and contributing to collective expenses. House ownership provides independence, but the owner must organize and fund maintenance directly. For a buyer who travels often or an out-of-area investor, the managed nature of a condo can be appealing. For someone who wants a large yard, a workshop, or freedom to renovate without condominium approval, a house often makes more sense.
Compare the Full Monthly Cost, Not Just the Price
A lower purchase price does not always mean a lower cost of ownership. The key is to look at the complete monthly picture: mortgage payments, property taxes, insurance, utilities, maintenance, and, for condos, monthly fees.
Condo fees can cover valuable services such as water, building insurance, snow removal, landscaping, security, and amenities. Some buildings include heating or other utilities. The amount alone does not tell the whole story. A higher fee may be reasonable when it supports a well-maintained building with meaningful services. A low fee may look attractive, but it can raise questions about whether the reserve fund and ongoing maintenance needs are being adequately supported.
House owners do not pay condo fees, but they should build their own maintenance reserve. Furnaces, windows, driveways, plumbing, appliances, roofs, and tree care do not arrive on a predictable schedule. A prudent budget treats upkeep as a recurring cost, not an occasional inconvenience.
Insurance also differs. Condo owners typically insure the contents of their unit, personal liability, and improvements or betterments inside the unit. House owners insure the structure and contents. Investors should request insurance quotes early, particularly for older homes, properties with rental suites, or buildings with prior claims history.
Do not overlook future capital expenses
For a condo, review the status certificate, financial statements, reserve fund study, budget, bylaws, and recent meeting minutes. These documents can reveal planned repairs, recurring concerns, litigation, insurance deductibles, fee increases, and special assessments. A building with a healthy reserve fund and disciplined management may be worth more than a similar unit in a poorly maintained corporation.
For a house, a detailed inspection is equally critical. Pay close attention to the age and condition of the roof, foundation, electrical panel, heating and cooling equipment, plumbing, drainage, and insulation. A well-priced home that needs immediate major work may not be the value it first appears to be.
Lifestyle: Space, Privacy, and Convenience
The best choice often becomes clearer when you picture a normal Tuesday, not just moving day. Condo living can place residents close to transit, restaurants, workplaces, and neighborhood services. It may offer fitness rooms, concierge services, shared outdoor spaces, or secure underground parking. For downsizers, first-time buyers, and people with busy schedules, that convenience can carry real value.
The trade-off is proximity. You may share walls, elevators, entrances, and building rules with neighbors. Pet restrictions, move-in procedures, renovation hours, and short-term rental policies can affect daily life. Even a spacious condo has limits that a detached property may not.
A house usually offers more private indoor and outdoor space. Families may value extra bedrooms, storage, a backyard, and room for guests. Owners may appreciate the ability to garden, install a shed, or personalize the property over time. However, more space requires more time and expense to heat, clean, repair, and maintain.
There is also a middle ground. Freehold townhomes can offer more space and autonomy than many condos, while condo townhomes may provide exterior maintenance support with a more home-like layout. The right comparison is rarely condo against detached house only. It is about matching the ownership model to your real priorities.
Condo Versus House for Rental Investors
Investors should assess each property through the lens of tenant demand, operating costs, financing, and management effort. A downtown or transit-connected condo may appeal to professionals looking for a turnkey rental close to work and amenities. A house in a family-oriented neighborhood may attract longer-term tenants who need bedrooms, parking, schools, and outdoor space.
Condos can be efficient rental assets, but investors need to confirm leasing rules before they buy. Review the declaration and bylaws for restrictions on rentals, minimum lease terms, pet policies, elevator booking procedures, and any requirement to provide tenant information to the condominium corporation. Short-term rental rules should never be assumed.
A house can offer more flexibility, including the potential for a legal secondary suite where zoning, permits, safety standards, and local requirements are met. It can also create more maintenance coordination. A leaking pipe, missed garbage collection, or snow-covered walkway is the owner’s issue to resolve, whether the owner lives nearby or not.
Good tenant selection matters in either property type. Verify credit, income, identity, and rental history, then use a clear lease and documented move-in condition report. Reliable rent collection, responsive maintenance coordination, and organized financial reporting protect returns long after the lease is signed.
Focus on the property’s workable numbers
Avoid assuming that a condo is always low-maintenance or that a house will always produce higher rent. Compare realistic rent against all carrying costs, including vacancy allowance, property taxes, insurance, utilities the owner pays, condo fees, repairs, financing, and management. Consider how easily the unit can be re-rented if a tenant gives notice.
The strongest investment is usually not the one with the most appealing listing photos. It is the property with sustainable cash flow, a clear tenant profile, manageable risks, and a location that supports demand over time.
Questions to Answer Before You Buy
Before choosing either option, be specific about what you can afford each month, how long you expect to own the property, and how much maintenance responsibility you are willing to accept. Buyers should also consider future needs. A condo that works for one person today may feel restrictive after a job change, a growing household, or a shift to working from home. A house that feels perfect may become burdensome if you plan to travel frequently or prefer a more simplified routine.
For investors, ask whether the property will remain appealing to renters after the first lease ends. Check nearby transit, parking, schools, employment centers, building reputation, and competing rentals. If you are purchasing a condo, make the status certificate review a condition you take seriously. If you are purchasing a house, do not treat the inspection as a formality.
A trusted real estate and property management partner can help translate these questions into a practical decision. Sunview Real Estate supports buyers and investors with local market guidance, tenant screening, rent collection, maintenance coordination, and clear reporting, so the property can serve your goals after closing as well as on closing day.
The right property is the one whose costs, responsibilities, and rental potential still make sense after the excitement of the showing fades. Take the time to test the numbers, read the documents, and choose the ownership model you can manage with confidence.